House price predictions bring no joy to first-home buyers
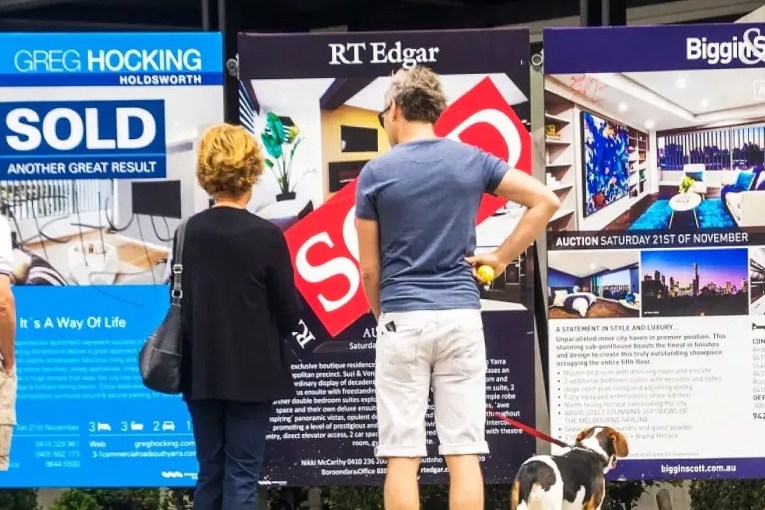
House prices are tipped to fall by up to 10 per cent in 2023. Photo: TND
The big banks are tipping the housing market will take a breather in 2023, with Commonwealth Bank expecting a price fall of 10 per cent that year and the ANZ expecting a more modest fall of 4 per cent.
But first-home buyers struggling to break into the market shouldn’t expect too much joy as a result, because the predicted falls are only expected after two years of massive gains.
Record-low interest rates and a range of government incentives pushed up house and unit prices by 24.2 per cent and 13.3 per cent respectively over the 12 months to October 31, CoreLogic figures show.
And the big banks are expecting growth to continue into 2022.
CBA predicts a 7 per cent rise next year, while ANZ expects 6 per cent and NAB 3.6 per cent.

Looked at on a graph the price rises in recent years have been dramatic.
“Those price rises have now been baked into the market because of lower interest rates,” said Angie Zigomanis, director with property consultants Charter Keck Cramer.
The banks are predicting modest price falls in 2023 because interest rates are expected to rise a little as the RBA moves to keep a lid on inflation.
“That will take a little steam out of the market,” said Mr Zigomanis, adding that the ‘escape to the country’ trend triggered by the pandemic would soon run its course.
“There will also be a reduced demand for detached housing as there are a finite number of people wanting to move from units following the effects of the pandemic.”
But the expected falls in 2023 will much smaller than the recent run up in prices.
House prices outstrip wages
As the graph below shows, house prices have risen far quicker than wages.
Since the beginning of this century, CoreLogic’s wage price index (measuring wages growth) has lagged well behind home price increases, and the result is that home prices relative to wages are higher now than they have ever been.
“In the June quarter, home prices were 11.8 times household disposable income,” said former ANZ chief economist Saul Eslake, who now operates independently.
“Ten years ago it was 9.1 times and throughout the 1990s it was below six times.”
Lower interest rates mean the proportion of income required to service a mortgage hasn’t changed much over the years.
But the major difficulty for first-home buyers is saving a deposit.
Massive deposit hurdle
“The problem, of course, is that the deposit gap keeps getting wider as house prices rise and lower interest rates make it harder to save for a deposit,” Mr Eslake said.
That means as house prices go up people without access to family or investment money find that the deposit they need to save keeps outpacing their ability to save it.
Mr Eslake said record-low interest rates and the drive by banks to lend more, which was in part a result of governments “throwing record amounts of money at would-be home builders and home buyers has contributed to the escalation in prices”.
Apartment prices have risen more slowly than house prices because there has been less demand for units.
Indeed, there was an oversupply in some apartment markets as a result of foreign students being barred from entry to the country because of the pandemic.
CBA economist Gareth Aird said: “We look for prices to peak in late 2022 around 7 per cent higher than end‑2021 levels. We then expect an orderly correction in dwelling prices of 10 per cent in 2023.”
Mr Aird believes this will happen because he expects the RBA to lift the cash rate from today’s record-low 0.1 per cent to 1.25 per cent by the third quarter of 2023.