A year ago in these pages I suggested that the Reserve Bank was in danger of getting left behind by inflation, and that we were all therefore “in danger of getting left behind by galloping interest rates”.
RBA governor Philip Lowe had just told the House of Representatives standing committee on economics that it was “plausible … that an interest rate increase will be on the agenda some time later this year”.
An interest rate increase? On the agenda? Try eight, actually happening. Dr Lowe and his colleagues did get left behind; they made a mistake, and that’s not even counting the repeated prediction that rates wouldn’t change until 2024.
What was the mistake, exactly? Well, they waited too long to start raising rates, and as I wrote in that piece last February, the longer you wait the more rates have to rise, and more quickly.
Getting left behind … again
Now they’re in danger of getting left behind again – on the way down – because they have resumed the grotesque idea that human misery is the only way to control prices – that is, using unemployment and putting families into mortgage stress.
As 2022 began, the global debate was whether inflation was transitory or permanent. The world’s economists divided up into teams – Team Transitory and Team Permanent.
Well, Team Transitory won – global inflation is now on the wane.
It’s true that the Australia Bureau of Statistics’ monthly inflation indicator jumped 0.8 per cent in December, taking the annual inflation rate back above 7 per cent after it fell to 6.9 per cent in November.
But that was due mainly to a 2.4 per cent lift in fruit and vegetable prices because of the floods, and a 5.6 per cent pop in petrol and diesel in the month because of global oil prices.
The solution to this? Markets are now predicting another rate hike next month, to cause more housing stress and higher unemployment.
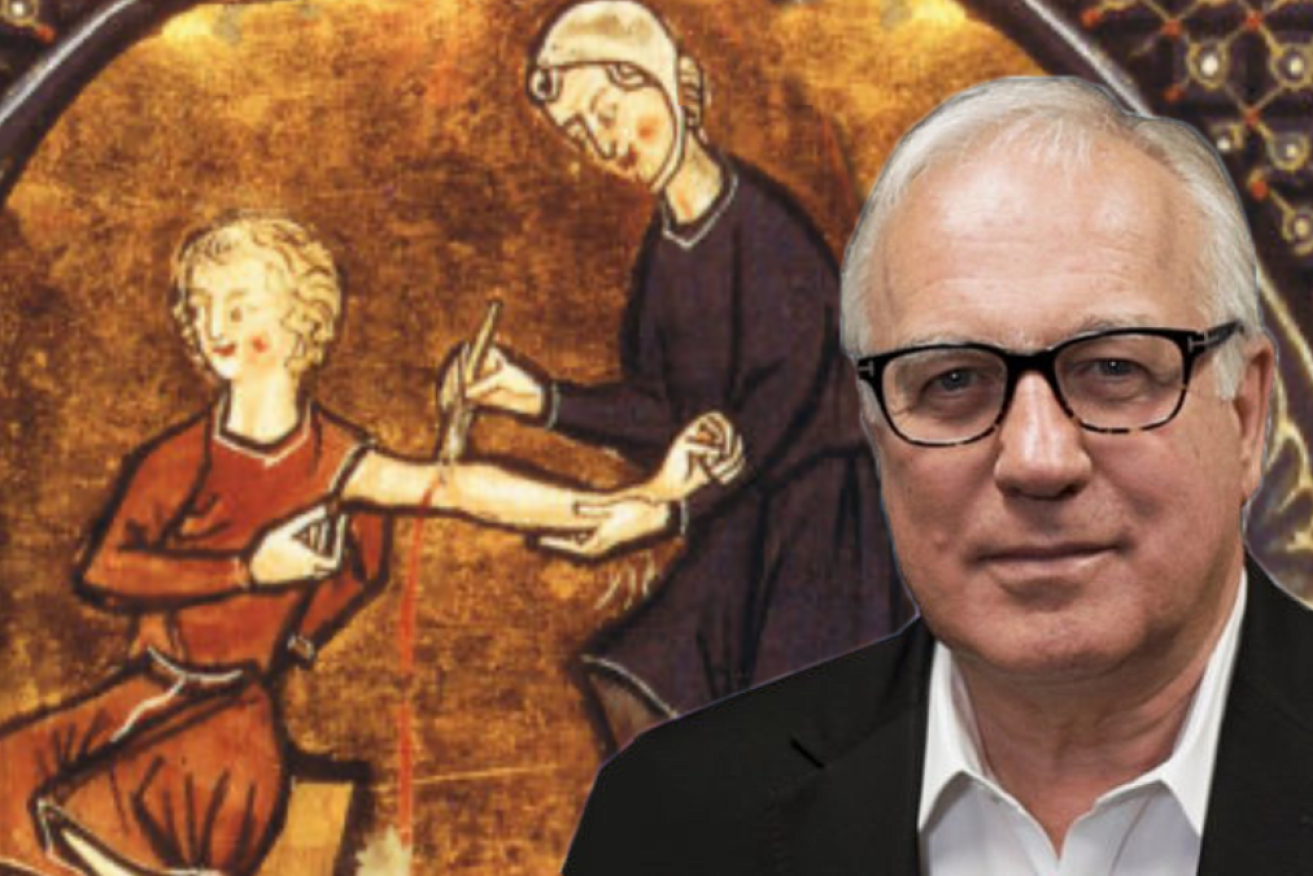
As US economist Lyn Alden tweeted the other day: “In the future, the idea of central policymakers purposely creating more unemployment as the primary way to contain inflation might be seen as the economic equivalent of bloodletting in medicine.”
The scientific basis for bloodletting came down from the ancient Greek physician Hippocrates’ idea that there were four key humours in the human body: Black bile, yellow bile, phlegm and blood.

Hippocrates had the wrong idea about bloodletting to cure physical ailments – and it’s not great for inflation either. Photo: Getty
Bleeding a patient to health was based on menstruation, which Hippocrates imagined was designed to purge women of bad humours, and bleeding was still being used by barber-surgeons well into the 19th century, because the medical profession couldn’t think of anything else to do, and they had to do something.
The scientific basis for using unemployment to control inflation is the Phillips Curve, proposed by New Zealand economist William Phillips in a seminal 1958 paper titled: ‘The Relation between Unemployment and the Rate of Change of Money Wage Rates in the United Kingdom, 1861-1957’.
Phillips didn’t explicitly link unemployment and inflation – that was done later by Paul Samuelson and Robert Solow and then Milton Friedman, who created the policy structures to put it into practice.
Friedman and Edmund Phelps at Columbia University said that any sustained effort to keep unemployment low would lead not just to high inflation but to ever-accelerating inflation. In 1979-80, Fed chairman Paul Volcker used unemployment to end The Great Inflation and thus became the immortal hero of central bankers to this day.
As a result, governments and central banks gave up trying to achieve full employment and instead aimed for a “non-accelerating inflation rate of unemployment” (NAIRU) instead, which they had to guess at, but was, and is, well above zero. The latest guess for Australia’s NAIRU is 4.5 to 5 per cent.
More broadly the dominant economic paradigm became all about making tough choices now for future happiness.
In a way, the Phillips Curve led to what became known as neoliberalism, because it established the limits of government action and the primacy of private markets.
The GFC and the pandemic changed everything, not because of the disinflation caused by sharp jumps in unemployment – which tended to confirm the Phillips Curve – but because inflation didn’t go back up when unemployment fell back down again, including when it fell below 4 per cent un the US in 2019 and 5 per cent in Australia in 2021.
Bringing inflation back from the dead
The bloodletting had stopped working. In 2015 Denmark, Switzerland and the European Central Bank actually took their policy interest rates negative – below zero! – and while the US Fed and the RBA couldn’t bring themselves to try that magic spell to bring inflation back from the dead, they printed money instead and, in the case of the RBA, declared that rates would stay near zero for three years.
Then in 2022 inflation rose again and normal transmission was restored, to the relief of central bankers who, as one, got out their Paul Volcker textbooks and returned his picture to their walls.

Was fallout from the pandemic to blame for rising inflation? Photo: AAP
But is inflation now – or ever – really the result of low unemployment? Or is it caused by supply shocks, this time from the pandemic and climate change, as well as excess demand funded by government rescue spending during COVID?
Doesn’t matter.
There is one tool to control inflation and that’s interest rates. Moreover, the gospel according to St Paul Volcker emphasised that even a supply-based inflation such as that caused by the oil shocks of the 1970s can only be controlled by unemployment.
Yet we now have a small, brief lesson in the alternative: On December 23, the acting Treasurer, Katy Gallagher, signed Competition and Consumer (Gas Market Emergency Price) Order 2022 which imposed a price cap on gas of $12 per gigajoule.
It’s only for 12 months, and the level of the price cap is not very troublesome for the companies involved – it’s certainly no repeat of the 1948 referendum that would have given the government constitutional power to control rents and prices (which was defeated) – but perhaps it’s a start.
The historical problem with direct price controls, of course, is that they are imposed by politicians, who are sometimes incompetent or corrupt, or both, whereas those conducting monetary policy are independent of politics (which doesn’t necessarily make them competent).
Then again, the ACCC gets involved in quite a lot of price control and monitoring, independent of politics. Should its mandate expand to an economic one, supporting the RBA’s inflation mandate and covering inflation more broadly than the specific utility and infrastructure prices it governs now?
I do think future economists will look back on the practice of using the misery of unemployment to control prices and wonder “what were we thinking?”
But that seems a long way off at as we begin 2023, with a temporary, unchallenging, price cap on gas, and an RBA trying to get unemployment up.
Alan Kohler writes for The New Daily twice a week. He is also founder of Eureka Report and finance presenter of ABC news